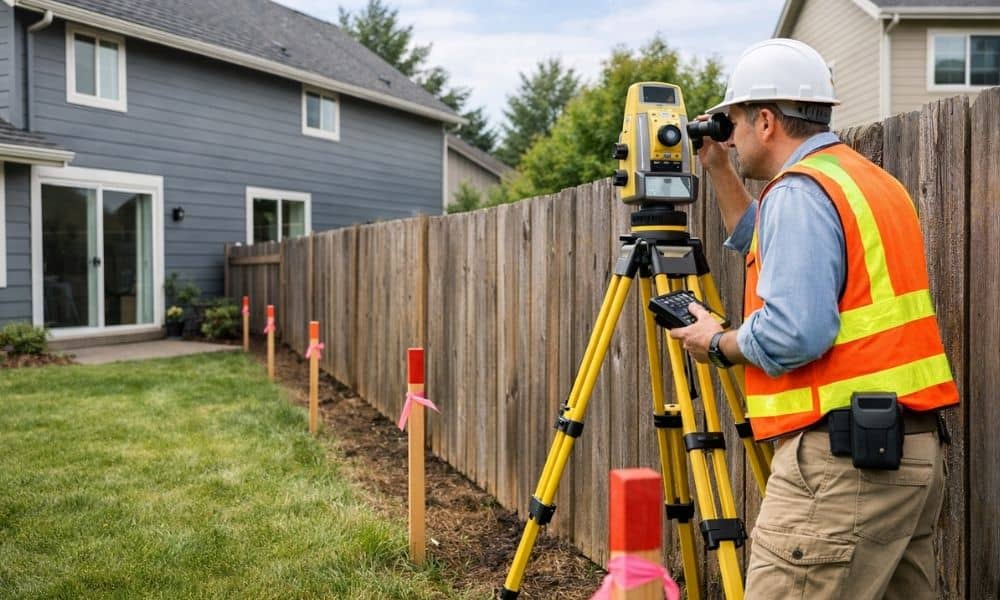
Your neighbor’s fence sits a few inches into your yard. Nobody notices for ten years. Then you list your house, and the buyer’s lender asks for a fresh survey. Suddenly, those few inches turn into a real question. Who pays to find out where the line actually sits?
Boundary survey costs cause more neighbor arguments than the fences themselves. Here’s how the money usually works, and where the rules can surprise you.
The Default Rule: Whoever Requests the Boundary Survey Usually Pays
In most fence disputes, the person who orders the survey pays for it. This is true even if the survey later proves them right. Ordering a survey is a request for facts, not an admission of fault.
If you think your neighbor’s fence crosses your line, you hire the surveyor. You pay the invoice when the work is done. Your neighbor isn’t required to chip in, even if the survey shows you were correct all along.
This surprises a lot of homeowners. It feels unfair to pay hundreds of dollars just to prove someone else built in the wrong spot. But surveyors get paid for their labor, not for the outcome. The person who asked for the work carries that cost, unless a later agreement or court order changes it.
A few practical notes:
- Get a written quote before you hire anyone.
- Confirm the surveyor is licensed in your state.
- Ask for a stamped, recorded plat, not just a verbal opinion.
When a Court or Settlement Splits the Cost Between Neighbors
If a fence dispute goes to mediation or small claims court, a judge or settlement can split the survey cost between neighbors, or shift it fully to one side. This is different from the everyday “requester pays” rule.
Courts have room to be flexible. A judge might order the cost split 50/50 if both neighbors share blame for letting the confusion happen. Or a judge might hand the full bill to whoever built the fence in the wrong spot, especially if that person ignored old survey markers or a prior warning.
Mediation works in a similar way. Many neighbor disputes settle before trial, and the settlement can include a cost-sharing clause. This route is often cheaper and faster than a lawsuit. Ask a local attorney whether a small claims court in your state fits the size of your dispute before you file anything.
If the Fence Was Never Surveyed to Begin With, Who’s Liable for the Error?
When an old fence was built off a guess, a handshake, or a past owner’s assumption, liability usually falls on whoever built it. If that person is long gone or unknown, the current owner often ends up paying to fix the record.
Plenty of fences went up decades ago with no survey at all. Someone eyeballed the yard. Two neighbors agreed on a line with a handshake and nothing else. That kind of agreement can sometimes hold up under a legal idea called boundary by acquiescence, which some states recognize when neighbors have treated a line as fixed for many years.
But that rule doesn’t apply everywhere, and it doesn’t always survive a property sale. If you buy a home with an unsurveyed fence, you may inherit the uncertainty along with the yard. Fixing it usually means paying for a new survey. From there, you and your neighbor can formalize the line with a boundary line agreement, recorded at your county office.
Can You Recover Survey Costs From a Neighbor Who Encroached?
Paying for a survey and recovering that cost later are two separate steps. If the survey proves your neighbor’s fence, shed, or driveway crosses onto your land, you may be able to claim the survey fee as damages.
This detail gets skipped in most cost articles. You still pay upfront. But once encroachment is confirmed, that invoice becomes proof of your actual loss. Many small claims courts allow reasonable survey costs as part of a damages claim, alongside costs to remove or relocate the encroaching structure.
Steps that help your case:
- Keep the surveyor’s invoice and the final signed plat.
- Send a written demand to your neighbor before filing suit.
- Ask a local real estate attorney whether your state allows fee recovery, since rules vary widely.
How Title Insurance or a Home Warranty May (or May Not) Cover the Bill
Most standard title insurance policies exclude boundary and fence disputes that surface after closing. A home warranty almost never helps either, since those plans cover appliances and systems, not property lines.
Title insurance protects against problems that existed before you bought the home, like an undisclosed lien or a forged deed. Basic policies usually carve out boundary issues, unless you paid for an enhanced or extended policy at closing. Some lenders offer that option for a bit more money upfront.
Check your policy’s exclusions section before you assume you’re covered. If boundary disputes are excluded, and most are, the survey cost falls back on you as the property owner. Confirm this with your title company directly. Don’t guess from memory.